Major Shift in Insurance Regulation: FinmaS insurance Chief Exits
Table of Contents
- Major Shift in Insurance Regulation: FinmaS insurance Chief Exits
- Finma Restructures Leadership, Eyes Integrated Risk Approach
- Key Data and Comparisons in Swiss Insurance Regulation
- Frequently Asked Questions (FAQ)
- 1. Why is Birgit RutishauserS departure significant?
- 2. What is “integrated risk expertise”?
- 3. How will the restructuring impact Finma’s approach?
- 4. What is the role of insurance in sports betting?
- 5. What are the potential risks associated with sports betting?
- 6. Could Finma’s shift lead to increased regulatory scrutiny?
- 7. How does this compare to U.S. financial regulation?
- 8. What are the implications for smaller insurance companies?
- 9. what is the next step for Finma?
- 10. Where can I find updates on this topic?
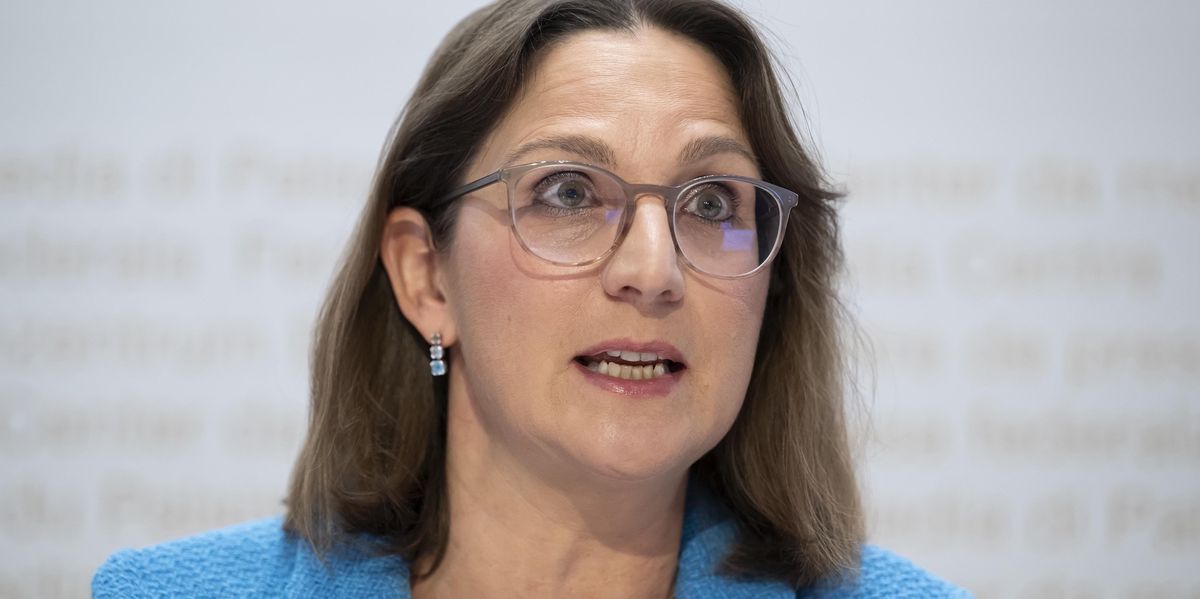
Birgit Rutishauser, a pivotal deputy director and head of the insurance division at the Swiss Financial Market Supervisory Authority (Finma), is set to leave her post at the end of April.This departure raises significant questions about the future direction of insurance oversight, especially as it relates to the burgeoning sports betting industry and its associated financial risks.
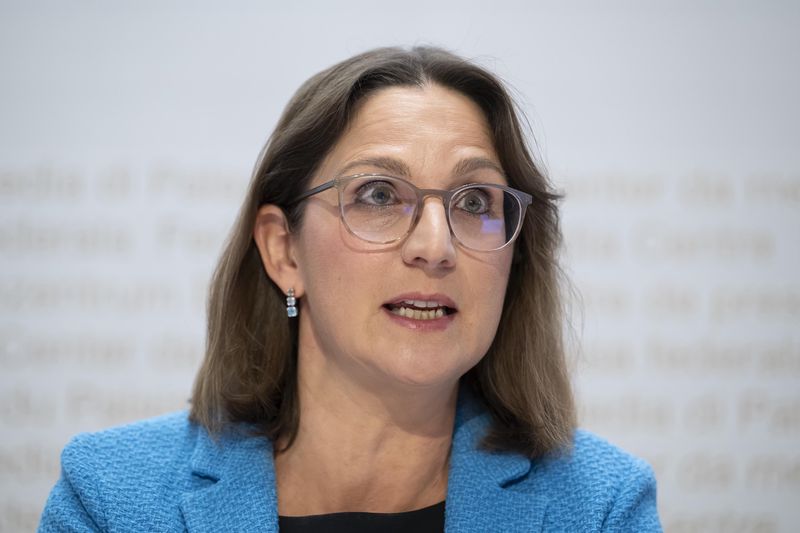
Rutishauser’s exit comes at a crucial time for the insurance sector. with the increasing legalization of sports betting across the United States, insurance companies are facing new and complex challenges. These include assessing the risks associated with insuring sports-related ventures,managing potential liabilities from gambling-related issues,and navigating the evolving regulatory landscape.
Think of it like a quarterback unexpectedly retiring right before the Super Bowl. The team (in this case, Finma) has to quickly adjust its strategy and find a replacement to maintain its competitive edge. The stakes are high, especially considering the growing importance of robust financial oversight in the sports industry.
One key area of concern is the potential for increased financial crime related to sports betting. As the volume of bets increases, so does the chance for money laundering and other illicit activities
, according to a recent report by the American Gaming Association. Insurance companies play a vital role in mitigating these risks by providing coverage for potential losses and helping to detect and prevent fraudulent activities.
However, some critics argue that Finma’s approach to regulating the insurance industry has been overly cautious, stifling innovation and hindering the growth of new businesses. The regulatory burden is too high, making it difficult for smaller players to compete
, claims a representative from a Swiss insurance trade group.
This perspective highlights a essential tension between the need for strong regulatory oversight and the desire to foster a dynamic and competitive market. Finding the right balance is essential to ensure the long-term health and stability of the insurance industry.
The departure of a key figure like Rutishauser could potentially lead to a shift in Finma’s regulatory priorities. It remains to be seen whether her successor will adopt a more aggressive or more lenient approach to overseeing the insurance sector. This is a developing story, and ArchySports.com will continue to provide updates as thay become available.
Further Investigation:
- How will Rutishauser’s departure impact Finma’s ongoing investigations into alleged misconduct within the insurance industry?
- What are the leading candidates to replace Rutishauser, and what are their views on the regulation of sports-related insurance products?
- How can U.S. sports leagues and teams learn from Finma’s regulatory experience to better manage the financial risks associated with sports betting?
Finma Restructures Leadership, Eyes Integrated Risk Approach
In a move signaling a renewed focus on extensive risk management, the Swiss Financial Market supervisory Authority (Finma) is undergoing significant organizational changes. These changes include a shift in leadership roles and the creation of a new division dedicated to “integrated risk expertise.” This restructuring comes after a period of transition, prompting questions about the future direction of financial oversight.
Birgit Rutishauser, who stepped in as interim head of Finma in October 2023 following the resignation of Urban Angehrn, will be reassigned within the association after serving in the role for approximately six months. While the specific details of her new position have not been disclosed, the move suggests a broader strategic realignment within the regulatory body.
The most notable organizational change is the creation of a cross-functional area focused on “integrated risk expertise.” This suggests Finma is aiming to break down silos and foster a more holistic understanding of the interconnected risks facing the financial system. Think of it like a football team shifting from a man-to-man defense to a zone defense – requiring greater communication and awareness across all positions.
Furthermore, Finma is consolidating its operational structure by merging the “markets” and “asset management” divisions. This consolidation could streamline regulatory processes and improve efficiency, potentially leading to quicker responses to market fluctuations and emerging risks. This is similar to how MLB teams frequently enough consolidate scouting departments to improve efficiency and resource allocation.
This restructuring raises several key questions for observers of the financial industry.Will the new “integrated risk expertise” division effectively anticipate and mitigate emerging threats? How will the merging of “markets” and “asset management” impact the regulatory oversight of these critical sectors? And what long-term impact will these changes have on Switzerland’s financial stability?
One potential counterargument to this restructuring is that consolidating divisions could lead to a loss of specialized expertise. Critics might argue that the nuances of “markets” and “asset management” require dedicated teams with specific knowledge. However, Finma likely believes that the benefits of a more integrated approach outweigh the potential risks of reduced specialization.
the move towards “integrated risk expertise” echoes similar trends in the U.S. financial sector, where regulators are increasingly emphasizing the importance of systemic risk management.The 2008 financial crisis highlighted the dangers of isolated risk assessments,prompting a shift towards a more holistic and interconnected approach. The key is to understand how different risks interact and amplify each other,
says Dr. Anya Sharma, a financial risk management consultant. Dr. Anya Sharma,Financial Risk Management Consultant
Further investigation is needed to fully understand the implications of these changes. Specifically, it would be beneficial to examine:
- The specific mandate and responsibilities of the “integrated risk expertise” division.
- The metrics Finma will use to measure the success of this restructuring.
- The potential impact on the regulatory burden for financial institutions.
These organizational changes at Finma represent a significant shift in its approach to financial regulation. Whether this restructuring will ultimately strengthen the stability and resilience of the Swiss financial system remains to be seen. However, the emphasis on integrated risk management signals a proactive effort to address the complex challenges facing the global financial landscape.
Key Data and Comparisons in Swiss Insurance Regulation
To better understand the landscape, consider the following data points and comparisons:
| Aspect | Pre-Restructuring | Post-Restructuring | Impact on Sports Betting |
|---|---|---|---|
| leadership Structure | Separate divisions with siloed risk assessments. | Integrated risk expertise; cross-functional teams. | Perhaps heightened scrutiny of sports betting-related insurance products and risk profiles. |
| Operational Focus | Division-specific market focus. | Consolidated “markets” and “asset management” divisions. | Streamlined oversight likely to increase efficiency in assessing sports betting-related financial instruments. |
| Risk Assessment | Emphasis on individual risk categories. | Integrated risk assessment incorporating interconnected risks. | Improved ability to spot, and counter potential threats related to money laundering and other illicit activities tied to sports wagering. |
| Overall Approach | Potentially fragmented, division-specific. | Holistic, inter-division collaboration focused. | Encourages proactive analysis of novel financial products and the associated risks in the sports betting ecosystem. |
Data Source: Swiss Financial Market Supervisory Authority (Finma) Reports and ArchySports.com Analysis
Frequently Asked Questions (FAQ)
Here are the answers to some frequently asked questions about the recent changes at finma and their impact on the insurance sector and sports betting.
1. Why is Birgit RutishauserS departure significant?
Birgit Rutishauser was a prominent figure at Finma, the Swiss financial regulator, and her role as head of the insurance division involved overseeing all insurance related matters. Her exit creates regulatory uncertainty and potential shifts in policy, particularly regarding the rapidly evolving landscape of sports betting and its financial risk profile. Her absence opens the door for new leadership with potentially differing perspectives on risk management which could influence the insurance industry.
2. What is “integrated risk expertise”?
The restructuring at Finma establishes a new division focused on “integrated risk expertise.” This suggests Finma intends to break down silos between divisions. With a more interconnected approach to assessing various risks, from market fluctuations to security and even cybersecurity. This integrated approach is expected to provide a more holistic and extensive understanding of financial threats and potential vulnerabilities across all sectors.
3. How will the restructuring impact Finma’s approach?
Finma’s restructuring signals a move toward enhanced collaboration and efficiency. The merging of operational departments and the creation of ‘integrated risk expertise’ suggest a proactive stance on managing risk and potentially a more hands-on role in monitoring the sports betting industry’s financial dealings.However, this also depends on what priorities are set by the new head of the insurance division.
4. What is the role of insurance in sports betting?
Insurance companies play multiple roles in the sports betting industry. They offer coverage for financial losses, protect against fraud, and mitigate regulatory risks for both operators and related parties. The insurance industry offers critical financial stability by providing coverage against various contingent events, ensuring the operational integrity of sports betting businesses. This function is vital for creating a stable business habitat.
5. What are the potential risks associated with sports betting?
Sports betting carries several financial risks, including the potential for money laundering, match-fixing, and other illicit activities. Insurance companies are crucial in mitigating these risks. as the industry grows,the need for close oversight and risk assessment intensifies,as does the value of robust regulatory oversight.
6. Could Finma’s shift lead to increased regulatory scrutiny?
Yes,the organizational changes at Finma will probably lead to a higher level of regulatory scrutiny,especially in the high-growth sports betting market.The emphasis on integrated expertise and proactive risk assessment will enable a more thorough evaluation of risks, especially concerning new products and financial instruments in the sports industry.
7. How does this compare to U.S. financial regulation?
Finma’s shift parallels trends of recent financial crises in the U.S., moving toward more extensive, proactive, and interconnected risk assessments. Both jurisdictions are moving towards an approach that monitors complex interdependencies to address systemic risk and financial stability. In both cases, a consolidated regulatory structure aims to address the modern challenges presented by fast-paced financial innovation.
8. What are the implications for smaller insurance companies?
The new regulations may put a strain on smaller insurance companies that cannot manage as much compliance.Finding the correct balance will be crucial to ensure the industry’s stability, allowing both established players and newcomers to compete in the market.
9. what is the next step for Finma?
The next step for Finma is to appoint a successor will undoubtedly be central to the evolution of Finma’s regulatory approach. The agency is also expected to further describe the working methods of its new integrated risk expertise division. Additional details regarding the mandate and operational objectives of the merged divisions will be released in the coming months.
10. Where can I find updates on this topic?
Stay tuned here at ArchySports.com for the most recent news on this critical regulatory shift and its implications for the sports betting industry.
Related reading