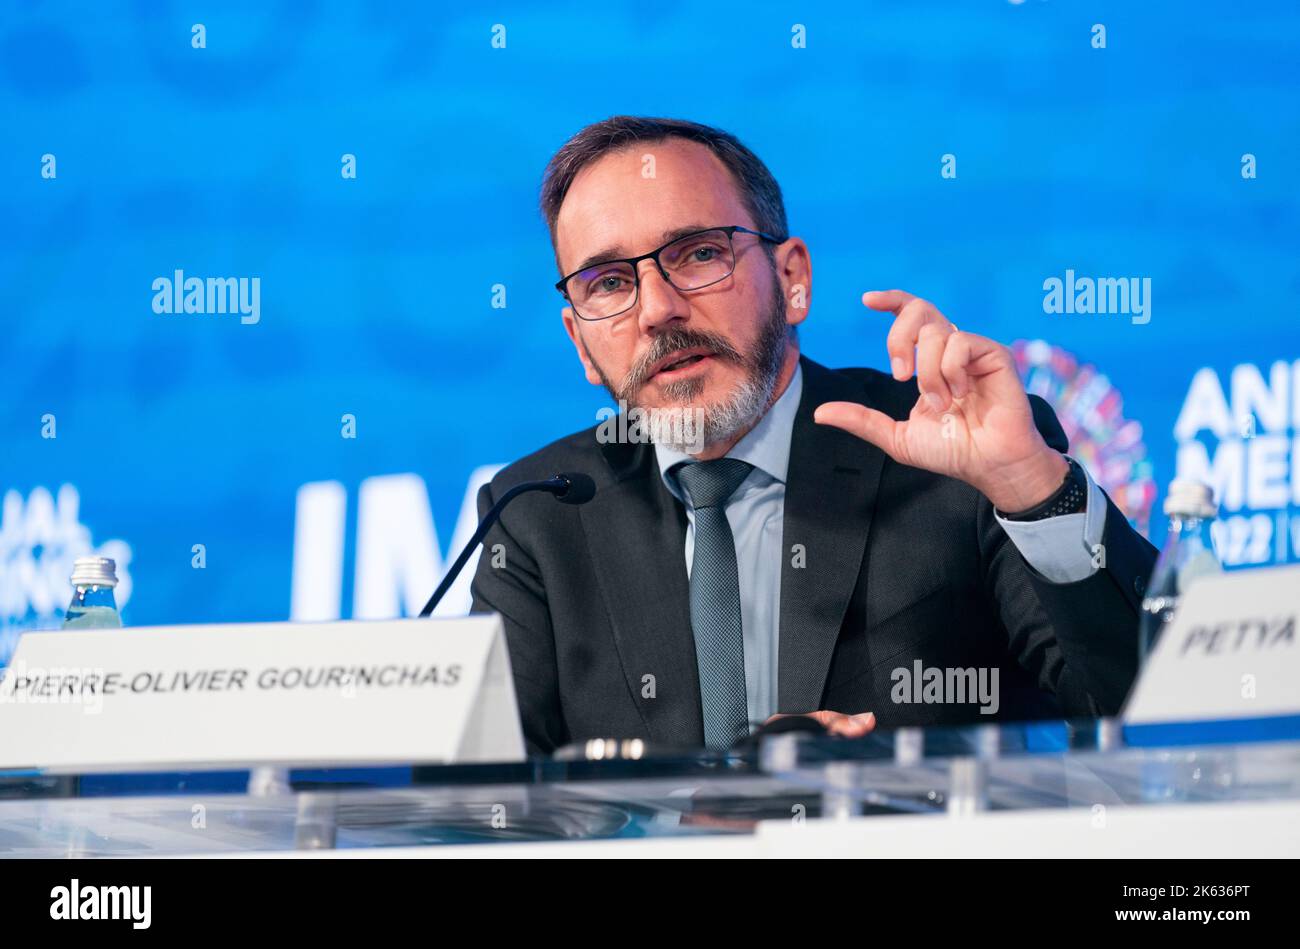
France faces a mounting financial crisis characterized by a projected 2026 public deficit of 5.4% and widening bond spreads, driven by a persistent political paralysis and an inability to implement difficult fiscal choices, according to former International Monetary Fund chief economist Pierre-Olivier Gourinchas.
The 2026 Budget Reality and Bond Market Pressures
Yields on French government bonds have climbed steadily, separating France from broader global yield trends and raising borrowing costs significantly.
Before the parliamentary dissolution in June 2024, the yield spread between French and German bonds hovered between 60 and 80 basis points, compared to 30 to 40 points prior to that year. That spread recently reached 130 basis points, with a peak exceeding 150 points on October 2. With national debt hovering near 120% of gross domestic product, an extra 70 basis points translates over time to roughly 0.8 percentage points of GDP in added debt-servicing costs for the state.
Expert Savings Projections and Legislative Hurdles
An expert commission composed of Xavier Jaravel, Xavier Ragot, Natacha Valla, and Jean-Luc Tavernier calculated that France requires roughly €125 billion in savings achieved through a combination of spending cuts and tax increases to stabilize public accounts over the long term.
That legislative proposal includes freezing a portion of retirement pensions and index points, trimming ministerial spending, and extending the corporate exceptional contribution. If political parties fail to reach an agreement on this legislative package, a default to special emergency laws threatens to extend the budgetary deadlock and bypass necessary fiscal adjustments.
International Comparisons and European Central Bank Policy
Contrasting the French fiscal trajectory with other nations, Gourinchas pointed out that while the United States maintains a public deficit between 6% and 7% without immediate reduction plans, recent American tax cuts on top earners leave future administrations with policy flexibility. By contrast, France suffers from severe political resistance to structural reforms, such as the contentious pension adjustments.
Market observers frequently ask whether the European Central Bank will intervene to protect French debt if turmoil worsens. Gourinchas explained that the ECB operates under a strict price-stability mandate for the entire eurozone and is legally prohibited from monetizing state debt. While the central bank maintains tools like the Transmission Protection Instrument (TPI) to combat unjustified market contagion—as seen with recent Italian yield movements reaching 120 basis points—the TPI is designed to protect neighboring economies rather than rescue a government suffering from years of unaddressed fiscal drift.
The Outright Monetary Transactions (OMT) program, described as a financial bazooka created in 2012 following Mario Draghi’s “whatever it takes” pledge, remains unactivated. Utilizing it would require negotiating a formal stabilization program with the European Stability Mechanism, effectively placing national spending and taxation choices under external oversight and trusteeship.
Critical Near-Term Checkpoints for French Debt
Financial markets remain highly sensitive to upcoming decisions regarding the parliamentary budget debate and forthcoming credit rating evaluations. Moody’s and Standard & Poor’s are scheduled to review French sovereign debt ratings, and any downgrade could force institutional investors to trim their holdings due to strict portfolio mandates. If borrowing rates approach 5% alongside a 200-basis-point spread, managing the national debt service will become substantially more difficult for French authorities.
Related reading